How to calculate crypto leverage and liquidation price
Last updated: September 10, 2026
Key Takeaways
- Post margin, and your position notional becomes a multiple of that margin based on the leverage used.
- At a $5,000 position and $1,250 of margin, the leverage is 4x.
- That is why 20x or 50x can be unsuitable for most readers.
- At 10x, the initial margin rate is 10%.
Crypto leverage and liquidation price come from the same handful of inputs: position size, leverage multiple, entry price, and the exchange’s margin rules. Once those four pieces are clear, you can estimate how much movement wipes out your margin and the exact level that triggers liquidation. Straightforward? Yes. Simple? Not always. This is information, not financial advice; for your own situation, especially if taxes or margin rules apply differently where you live, I would speak with a qualified adviser.
Who this is for, and who should do something else
Spot traders moving into perpetual futures, margin traders borrowing against collateral, and anyone checking a liquidation estimate before opening a position all fit here. I’m assuming you already know the difference between long and short, can read a trading ticket, and can find the exchange’s maintenance margin rate. Maintenance margin is the minimum equity the platform requires to keep the position open.
It does not apply cleanly if you are using a platform that hides its formula, mixes cross and isolated margin in one interface, or changes liquidation thresholds by tier. Many exchanges do exactly that. A generic calculator is only a rough guide when the contract has fee buffers, funding adjustments, tiered risk limits, or reduced collateral value for the asset you post. That matters even on a 1 BTC position — the liquidation price can shift when margin mode changes.
Trading in a regulated derivatives account? Or in a jurisdiction with position limits? Or through a broker that nets positions across instruments? Then the calculation can change again. In those cases, the platform’s own risk page is the source of truth. For any account where a mistake could trigger forced liquidation, I would use the exchange’s calculator and confirm the numbers against the contract specification before placing the order. Better boring than wrecked.
What leverage means in crypto, in plain terms
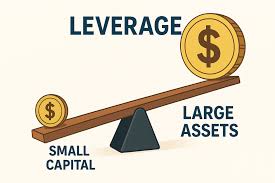
Leverage is the ratio between the size of the position you control and the margin you put up. A 10x position means your margin supports a position that is 10 times larger than the cash you commit. Put another way, the position notional scales up by the leverage multiple. Notional value is the full market value of the position, not the amount of margin.
The simplest estimate is:
Leverage = position notional ÷ margin
So if your position is worth $8,000 and you post $800, your leverage is 10x. If the position is $5,000 and your margin is $1,250, your leverage is 4x. Clean, right? This is the easy part.
What people miss is that leverage alone does not tell you where liquidation sits. Two traders can both be “10x long” and still have different liquidation prices because one pays more fees, one has a different maintenance margin, or one entered at a different price. An entry at $60,000 and a liquidation estimate at $54,000 is not the same risk as an entry at $3,000 and a liquidation estimate at $2,700, even though both are 10% away on paper.
Another thing matters: high leverage leaves very little room for ordinary volatility. Crypto routinely moves several percent in a day, and some coins move far more than that. That is why 20x or 50x can be unsuitable for most readers. I am not telling you what to use; I am saying the distance to liquidation gets small very quickly. Blink and it’s gone.
How do I calculate liquidation price on a crypto position?
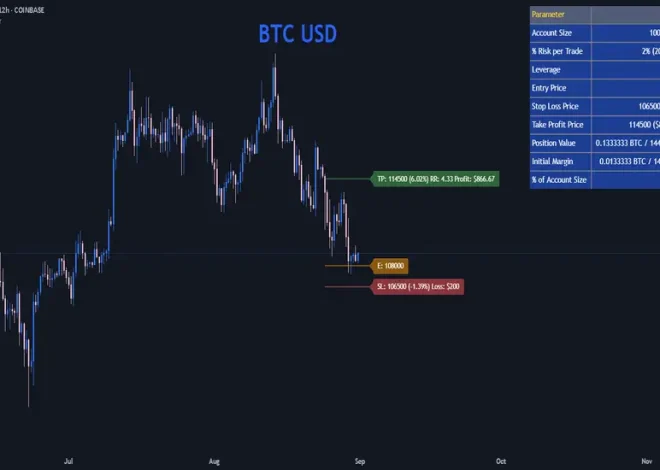
The liquidation price is the estimated market price at which your margin falls to the exchange’s maintenance threshold. In practice, four inputs drive the result: entry price, position size, margin, and maintenance margin rate. The exact formula varies by exchange, but the logic stays the same.
For a long position, liquidation happens when price falls enough that your equity is no longer above maintenance margin. For a short, it happens when price rises enough to do the same. Equity means your margin plus unrealized profit or minus unrealized loss.
A useful approximation for an isolated-margin position is:
- Long liquidation price ≈ Entry price × [1 – (Initial margin rate – Maintenance margin rate)]
- Short liquidation price ≈ Entry price × [1 + (Initial margin rate – Maintenance margin rate)]
Initial margin rate is the amount of margin required to open the trade, which is the inverse of leverage. At 10x, the initial margin rate is 10%. Maintenance margin rate is lower, and exchanges vary by contract and tier.
This approximation leaves out fees, funding, and tier adjustments. A tighter manual estimate uses equity directly:
- Start with your margin.
- Subtract opening fees if your platform removes them immediately.
- Subtract any fixed liquidation or closing fee buffer if the contract specifies one.
- Compare the remaining equity to the maintenance margin requirement.
- Solve for the price where unrealized loss equals the distance from your remaining equity to that maintenance threshold.
Because that is only an estimate, treat it as rough if the platform does not disclose the buffer. If the account is important or the rules are unclear, consult the exchange’s documentation and a qualified professional before relying on the number. For a long 1 BTC contract opened at $50,000 with $5,000 of margin, the position notional is $50,000 and leverage is 10x. If the exchange requires 0.5% maintenance margin, the maintenance threshold is not zero; the platform needs some equity left before forcing liquidation. The liquidation price will be above $45,000 if fees and buffers are included, but the exact number depends on the contract spec.
How to calculate it step by step
The most practical way to calculate both leverage and liquidation price is to separate the arithmetic from the exchange-specific rules. I’d do it that way every time.
- Write down the position notional. Multiply entry price by contract quantity. If you buy 0.25 BTC at $60,000, the notional is $15,000. Check the contract size and whether the platform quotes in coin or USD value. A mismatch here poisons every later number.
- Record the margin you are actually posting. Use the isolated margin assigned to that position, not your total account balance. If you post $1,500, keep that number separate from any spare funds in the wallet. If the platform uses cross margin, note that your whole account balance may be available, which changes the result materially.
- Calculate leverage. Divide notional by margin. In the example, $15,000 ÷ $1,500 = 10x. Check that the exchange’s displayed leverage matches your calculation. If it does not, look for hidden fees, unrealized P&L, or a contract multiplier.
- Find the maintenance margin rate. Look up the contract’s risk tier. Many exchanges publish a table with tiered maintenance rates; a larger position can require a higher rate. Make sure you are using the correct tier for your notional size. Use the wrong tier, and the liquidation estimate can shift sharply.
- Estimate your loss buffer. Subtract any opening fee, funding that is immediately charged, and liquidation fee buffer if the exchange states one. These are usually small compared with notional, but they are large enough to move a thin-margin position. If the platform does not disclose the buffer, treat your manual estimate as rough only.
- Compute the amount the market can move against you before liquidation. For a long, this is roughly the remaining equity above maintenance divided by contract quantity. For a short, it is the same idea in the other direction. Check the direction: longs lose when price falls, shorts lose when price rises. A sign error here is the usual faceplant.
- Convert that loss into a price level. Subtract the loss from the entry price for a long, or add it for a short. If the entry is $60,000 and the maximum adverse move is $4,200, the long liquidation estimate is around $55,800. Check whether your platform uses mark price rather than last traded price; if it does, the visible market price can differ from the liquidation trigger.
- Cross-check against the exchange calculator. Compare your manual estimate to the platform’s liquidation display, if available. If the difference is larger than a few ticks or a small percentage, something is missing: likely fees, funding, tiering, or cross-margin effects. Don’t trust the cleaner-looking number just because it is easier.
A worked example makes the process real. Suppose you open a long position worth $12,000 with $2,000 margin. Leverage is $12,000 ÷ $2,000 = 6x. If the contract’s maintenance requirement is 1%, the platform will not liquidate you at a 16.7% loss exactly; it will do so when equity falls to the maintenance threshold and any contract-specific buffer is exhausted. The exact liquidation price must come from the contract rules, but the leverage calculation is still simple and exact.
What changes the liquidation price after you open the trade?
Liquidation price is not frozen in every account type. It can move as the position changes, and that is where many traders get caught. Fees, funding, added margin, reduced margin, and changes in contract risk tier are the main drivers. On a perpetual futures contract, funding payments can arrive every 8 hours on many venues, but the interval is exchange-specific; they can nudge your equity up or down and shift the threshold.
Add margin to an isolated position, and liquidation moves farther away. Remove margin, and it comes closer. Increase position size, and your notional grows; the exchange may push you into a worse maintenance tier. If the market moves in your favor, unrealized profit can increase equity and improve the liquidation distance; if it moves against you, the opposite happens. Math gets hairy fast there.
Cross margin deserves special caution. In cross mode, your full wallet balance may support the position, so the liquidation price depends on other open positions and cash in the account. That can look safer than it is. One losing position can consume equity shared with another, and a small shock in one market can trigger liquidation across the account. I would treat cross margin as a portfolio risk tool, not a simple way to “give the trade more room.”
Mark price also matters. Many exchanges liquidate on mark price, which is an index-based estimate designed to reduce manipulation from sudden wicks. That means the price chart you watch and the price used for liquidation may not match exactly. If your exchange uses mark price, that is the number you need to track, not the last trade price.
When should I stop calculating manually?
Stop relying on a hand calculation when the platform’s risk rules are doing more work than the simple formula can capture. The downside is a false sense of precision, which is worse than a rough estimate.
Cross margin is enabled: your position is tied to the rest of the account — use the exchange risk engine or a qualified adviser for the account structure, because another position can change liquidation without warning.
The contract uses tiered maintenance margin: the rate rises with position size — recalculate using the exact tier, or the manual liquidation price will be too optimistic.
Funding is about to post within 1 to 8 hours: equity can change before the next price move — include funding in the estimate or wait until after the funding timestamp.
You have multiple open positions in the same account: portfolio equity affects the result — do not treat each position as isolated unless the platform explicitly does.
The exchange charges a liquidation fee or insurance-buffer adjustment: the true threshold shifts — read the contract specification and use the platform’s calculator rather than a generic formula.
The asset is extremely thinly traded or has wide spreads: the last price can mislead you — use mark price and be cautious, because slippage can turn a theoretical liquidation into a worse realized outcome.
If any of those applies and you are unsure how the platform treats it, the right move is to slow down, not to multiply harder. A qualified financial adviser or the exchange’s risk documentation can clarify the account mechanics.
The mistakes people actually make, and what they cost
The most common error is mixing up position size with margin. If you think $1,000 of margin means a $1,000 position, you will calculate leverage wrong by an order of magnitude. The correct alternative is to write down notional first, then margin.
Another mistake is using last traded price instead of mark price. On a fast market, the chart can print a wick far below the mark. The cost is a liquidation surprise. The correct alternative is to find the contract’s liquidation trigger method in the spec, usually mark price on derivatives platforms.
A third error is ignoring maintenance margin because the initial margin is already known. That makes the liquidation estimate too generous. The correct alternative is to use both rates, because liquidation begins when equity hits maintenance, not when it reaches zero.
A fourth mistake is forgetting fees and funding. Even small charges matter when the margin is thin. The correct alternative is to include opening fees, anticipated funding, and any liquidation buffer in the estimate, or treat the answer as approximate.
A fifth mistake is assuming the same leverage means the same risk across all coins. A 10x position in BTC and a 10x position in a less liquid altcoin do not behave the same because spreads, volatility, and contract rules differ. The correct alternative is to check the contract and the market’s actual volatility, not just the headline leverage.
What if the platform’s formula does not match mine?
That usually means the platform has added one of three things: a fee buffer, a funding adjustment, or tiered maintenance margin. Each of those can move the liquidation price by enough to matter on a tight position. The fix is not to keep re-running the same basic formula; it is to identify the missing input and use the contract’s own risk rules.
For inverse contracts, the math can also change shape because the margin and payout are denominated differently than in linear USDT-settled contracts. Inverse means the contract is settled in the base coin, such as BTC, rather than in a stablecoin. That makes the formula less intuitive, especially if you are trying to estimate liquidation from a USD price chart. In those cases, I would use the exchange’s calculator or consult a qualified professional before relying on a manual estimate.